fredag den 15. januar 2016

Macro Digest: Watch the Fed's next move.......

Just back from the US – there is new "dimension" to market today in my opinion:  The probability of Fed hiking 3-4 times as promised by Stanley Fischer and indirectly with Dudley today does not match markets probability – here is two charts to explain why:


84 bps means less than three hikes next 24 month vs a Fed at 3-4 in 2016 and same in 2017…..


This is the chance of a March hike…….

Market is nervous – and understandably so, but I think it mainly comes from the MASSIVE complacency which prevail even yesterday on the market. Every pundit on TV and in media: "loves …Europe…it's cheap!?" Really?

My S&P call for 2016 remains a wide range of 1800-2200 with 1H being nasty….. but keep an eye on the Fed hike probabilities……. There is chance for yet another…."pretend-and-extend" turn probably ignited by Draghi…..


Med venlig hilsen  |  Best regards
Steen Jakobsen  |  Chief Investment Officer


Saxo Bank A/S  |  Philip Heymans Allé 15  |  DK-2900 Hellerup
Phone: +45 39 77 40 00  |  Direct: +45 39 77 62 23  |  Mobile: +45 51 54 50 00


Research: http://www.tradingfloor.com/traders/steen-jakobsen

Please visit our website at www.saxobank.com


This email may contain confidential and/or privileged information.
If you are not the intended recipient (or have received this email
by mistake), please notify the sender immediately and destroy this
email. Any unauthorised copying, disclosure or distribution of the
material in this email is strictly prohibited.

Email transmission security and error-free status cannot be guaranteed
as information could be intercepted, corrupted, destroyed, delayed,
incomplete, or contain viruses. The sender therefore does not accept
liability for any errors or omissions in the contents of this message
which may arise as a result of email transmission.

tirsdag den 12. januar 2016

Steen's Chronicle: Back in the US of Averages

Steen's Chronicle: Back in the USA....

·        From potholes to politics, the US is a mess

·        Level of insightful debate is close to zero

·        Trump attracting huge crowds as Clinton's star fades

·        Economy is messy too and rewards will be few in 2016

·        Despite all of this, what we've got is a trader's market


 The United States of America is one big mess. Photo: iStock


By Steen Jakobsen


In the United States it feels like it's very late in a business cycle: the country's  infrastructure is worn out, the airports here are worse than most emerging markets I have visited, highways are 'potholes to infinity' and the sense of complacency is at the 99th quartile.

The media is terrible with a level of discussion and insight is very close to zero. There is more fundamental vision in one episode of Ellen than in all of the business and news channels combined.

The US presidential election is a mess. The GOP party can't decide whether to expel or support Donald Trump, who continues to fill stadiums and arenas with 15,000 plus people while his 'opponents' are lucky to get 500. Trump does not represent America in my opinion but he does represent the old GOP party platform, which is getting "more white and more angry" while the US at large is becoming more diversified and more in need of openness and change than ever before.

Hillary Clinton is in trouble – I'm beginning to doubt she even wants to become president, but the presidential election is hers to lose and she's been here before (losing to Obama from near certain victory) – what a mess. Meanwhile, the US remains on standstill while Obama tries to create, and here the operative word is 'create', his legacy.

Thank God for college football – I watched the Alabama vs Clemson final yesterday – that's the real America! A high scoring game, brave play calls and energy throughout. The motto of Alabama is simple: Finish, Finish, Finish.

I like that and I admire the strategy and execution it takes to manage a roster of 120 players and the mega egos on those team. That's what America should be in economic terms but isn't!

Maybe coach Saban should run for office – though I'm not sure the 'markets' would like the discipline needed and the hard work on which his and Alabama's success is derived from!

Back to the market - we have just released our Q1 Outlook called "Mind the gap" - which is about how the market doesn't get the change of the price of money.

Fed Atlanta's GDP now is pointing lower and lower: 


Meanwhile the Fed (and certainly Stanley Fischer) continue to talk of more hikes – four hikes is the ball park for 2016. This means wages and the labour market have priority over growth....for now.

My theory is that the Fed desperately wants to get Fed funds from 15 bps to 1.25% in order to be able to mitigate another financial crisis stemming from the clean out which has started in oil, emerging market and is about to enter the developed markets. 

Yes, indeed we are very late in the cycle, so late that assets will have a hard time returning positive yields in 2016, but for now my take from the US, being in Charlotte, NC, is that it will have to get worse before it improves.

Market are oversold, yes, China will eventually recalibrate, but the complacency, the lack of ideas and the willingness to invest is obvious to a travelling economist like me.

The US is 'surviving' on discounts! The retail sectors offers you a minimum 25%, even without asking for it, to reduce stocks - post discounts comes reality, and while the retail sector understands this I still think there is a major eureka moment for the markets and certainly for the US at large.

Strategy:

I've been short most of December and Q1. The strategy is to sell on the day and close by night as long as 'intervention' by central banks remains uncoordinated.

Still awaiting clear signal from the US dollar, which continues to trade in tight range vs EUR but stronger vs EM. The US dollar remains my catalyst – I will follow the lead from 1.05 or 1.12 break... if higher, risk on, if lower, risk off.

This is not a market to be brave, but it's a trader's market – you will not hear any complaints about that from me.

Safe travels,

Steen Jakobsen


– Edited by Clare MacCarthy


Steen Jakobsen is chief economist and CIO at Saxo Bank

RECOMMEND  COMMENT 

·        SHARE

·         

·         

·         

·         

DISCLAIMER

The Saxo Bank Group entities each provide execution-only service and access to Tradingfloor.com permitting a person to view and/or use content available on or via the website is not intended to and does not change or expand on this. Such access and use are at all times subject to (i) The Terms of Use; (ii) Full Disclaimer; (iii) The Risk Warning; (iv) the Rules of Engagement and (v) Notices applying to Tradingfloor.com and/or its content in addition (where relevant) to the terms governing the use of hyperlinks on the website of a member of the Saxo Bank Group by which access to Tradingfloor.com is gained. Such content is therefore provided as no more than information. In particular no advice is intended to be provided or to be relied on as provided nor endorsed by any Saxo Bank Group entity; nor is it to be construed as solicitation or an incentive provided to subscribe for or sell or purchase any financial instrument. All trading or investments you make must be pursuant to your own unprompted and informed self-directed decision. As such no Saxo Bank Group entity will have or be liable for any losses that you may sustain as a result of any investment decision made in reliance on information which is available on Tradingfloor.com or as a result of the use of the Tradingfloor.com. Orders given and trades effected are deemed intended to be given or effected for the account of the customer with the Saxo Bank Group entity operating in the jurisdiction in which the customer resides and/or with whom the customer opened and maintains his/her trading account. When trading through Tradingfloor.com your contracting Saxo Bank Group entity will be the counterparty to any trading entered into by you. Tradingfloor.com does not contain (and should not be construed as containing) financial, investment, tax or trading advice or advice of any sort offered, recommended or endorsed by Saxo Bank Group and should not be construed as a record of our trading prices, or as an offer, incentive or solicitation for the subscription, sale or purchase in any financial instrument. To the extent that any content is construed as investment research, you must note and accept that the content was not intended to and has not been prepared in accordance with legal requirements designed to promote the independence of investment research and as such, would be considered as a marketing communication under relevant laws. Please read our disclaimers:
- Notification on Non-Independent Investment Research 
- Full disclaimer


Med venlig hilsen  |  Best regards
Steen Jakobsen  |  Chief Investment Officer


Saxo Bank A/S  |  Philip Heymans Allé 15  |  DK-2900 Hellerup
Phone: +45 39 77 40 00  |  Direct: +45 39 77 62 23  |  Mobile: +45 51 54 50 00


Research: http://www.tradingfloor.com/traders/steen-jakobsen

Please visit our website at www.saxobank.com


This email may contain confidential and/or privileged information.
If you are not the intended recipient (or have received this email
by mistake), please notify the sender immediately and destroy this
email. Any unauthorised copying, disclosure or distribution of the
material in this email is strictly prohibited.

Email transmission security and error-free status cannot be guaranteed
as information could be intercepted, corrupted, destroyed, delayed,
incomplete, or contain viruses. The sender therefore does not accept
liability for any errors or omissions in the contents of this message
which may arise as a result of email transmission.

søndag den 3. januar 2016

China led? August vs. January

Interesting start to the year – the 'excuse' being weak China data and SHCOMP limit down, but how are we relative to August 'devaluation'?


Ouch! China does matter it seems……


Not CNY is 4.5% higher but off-shore CNH is weaker by 6.5% in same period:


g


Med venlig hilsen  |  Best regards
Steen Jakobsen  |  Chief Investment Officer


Saxo Bank A/S  |  Philip Heymans Allé 15  |  DK-2900 Hellerup
Phone: +45 39 77 40 00  |  Direct: +45 39 77 62 23  |  Mobile: +45 51 54 50 00


Research: http://www.tradingfloor.com/traders/steen-jakobsen

Please visit our website at www.saxobank.com


This email may contain confidential and/or privileged information.
If you are not the intended recipient (or have received this email
by mistake), please notify the sender immediately and destroy this
email. Any unauthorised copying, disclosure or distribution of the
material in this email is strictly prohibited.

Email transmission security and error-free status cannot be guaranteed
as information could be intercepted, corrupted, destroyed, delayed,
incomplete, or contain viruses. The sender therefore does not accept
liability for any errors or omissions in the contents of this message
which may arise as a result of email transmission.

onsdag den 30. december 2015

Happy New Year - 2015 was an amazing macro year, 2016 will be even more exciting.....

"May the New Year bring you courage to break your resolutions early! My own plan is to swear off every kind of virtue, so that I triumph even when I fall!" 
 
Aleister Crowley, Moonchild


2015 was  an exciting macro year, probably the most interesting since the GFC crisis started:


·        Policy makers went into overdrive and still failed – the lower for longer was dismissed, only for ECB to turn up late to a party ending. I love the timing of ECB and Europe,' better late than not at all' seems the motto of choice. The refugees will add to investment & growth in Europe in 2015 making ECB look out of line…..


·        Fed hiked "in spite" and will probably take Q1 growth as sign of confirmation – realizing too late that US economy can't tolerate higher rates..


·        Three years of falling emerging markets – consensus claims there will be a fourth year, of course I doubt that….


·        Oil going to sub-25?  Market seems to forget that Iran has been exporting oil forever, just not "legally"… plus OPEC needs production ceiling if Saudi et al wants to maintain the power of the region….


Finally, as 2015 close – the long warned signal for Fixed Income to sell off have come: today my "models" sold 10 and 30 Y US bonds plus went short both LQD and IEF – interesting close…!!!! Indeed….


2015 was the failure of central planning and the "asset allocation" year was the worst EVER – according to Bianco Research (Thank you Jim Perry !!!)


http://www.arborresearch.com/bianco/?p=113797


Let me end the year by wishing the best of luck and prosperity in 2016 – I promise it will be exciting year – Never has there been more opportunities, never have the policy makers been further away from the "the truth" and consensus than now, and of course our dear politicians are hopeless lost in a world of fantasies with reality catching up to their "pretend-and-extend" – You can run from Greece going bankrupt, but you can't hide from millions of refugees!


I had the pleasure of meeting many of you from this email list and I must say I was impressed by your commitment and willingness to discuss! Thank you for welcoming me all of you!


Safe travels into 2016 and Au Revoir,


Steen


Med venlig hilsen  |  Best regards
Steen Jakobsen  |  Chief Investment Officer


Saxo Bank A/S  |  Philip Heymans Allé 15  |  DK-2900 Hellerup
Phone: +45 39 77 40 00  |  Direct: +45 39 77 62 23  |  Mobile: +45 51 54 50 00


Research: http://www.tradingfloor.com/traders/steen-jakobsen

Please visit our website at www.saxobank.com


This email may contain confidential and/or privileged information.
If you are not the intended recipient (or have received this email
by mistake), please notify the sender immediately and destroy this
email. Any unauthorised copying, disclosure or distribution of the
material in this email is strictly prohibited.

Email transmission security and error-free status cannot be guaranteed
as information could be intercepted, corrupted, destroyed, delayed,
incomplete, or contain viruses. The sender therefore does not accept
liability for any errors or omissions in the contents of this message
which may arise as a result of email transmission.

torsdag den 17. december 2015

Steen's Chronicle: The Big Nothing? Final macro note of the year

Steen's Chronicle: The big nothing?


"I love to talk about nothing. It's the only thing I know anything about" – Janet Yellen……….sorry Oscar Wilde J


Finally! Saxo Bank's Outrageous Predictions is out:  Saxo OP-2016 Link to PDF and less important: Fed hiked!


My 'real' 2016 outlook in headlines will be this:


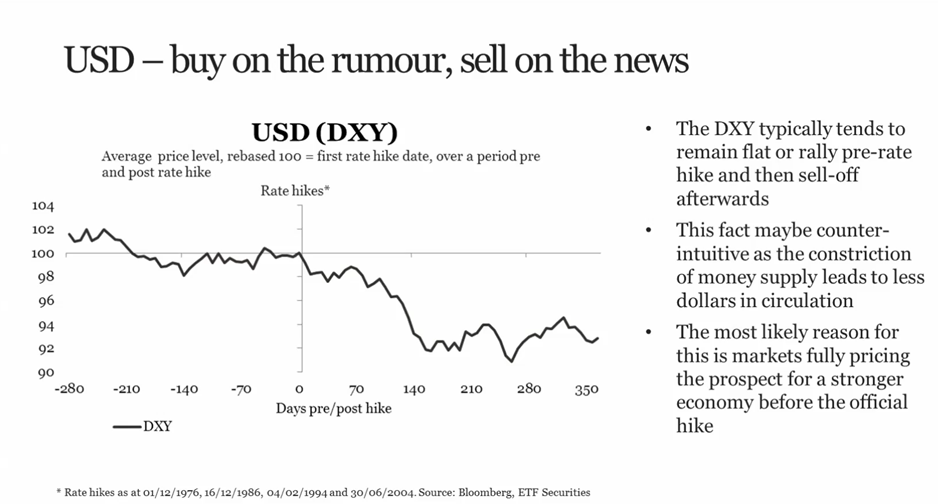
·       US Dollar will weaken – it will follow the "normal path" of weaker US$ post the first hike. https://pbs.twimg.com/media/CVEL-skVEAAyeOs.png:large

·       China will do better than expected – the easier monetary policy, but more importantly the "internationalization of RMB" will drive demand up, not down

·       Emerging market will be the best performing asset – it has both price and value being cheap. Argentina moving to floating currency is first good news in three years and more is to come.

·       2016 will be a year of two halves: A bad start, and a good finish. S&P will trade both 1.800 and 2.200 during the year, but overall 2016 is a "year of transition from zero bound, none working policies towards a new business cycle which will start with a "bust" and then a new start.

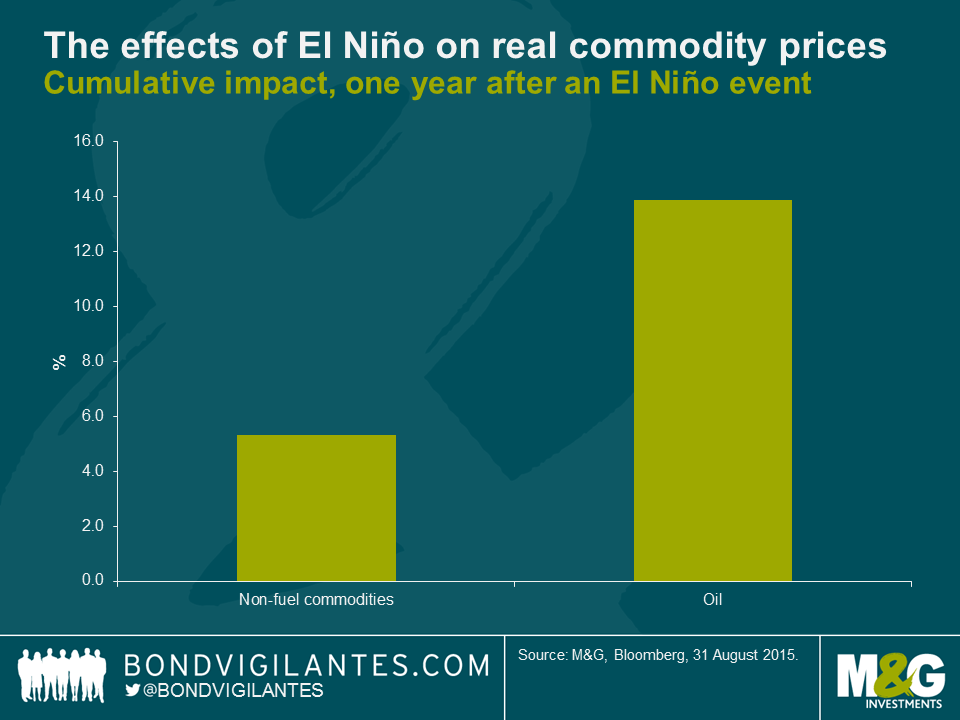
·       El Nino will impact inflation, growth and commodities positively: https://pbs.twimg.com/media/CWIgP6kUAAARm_6.png:large

·       Inflation will be higher next year – higher than expectations: El Nino adds 0.2%, base effect another 0.2% and then some demand pull and more credit flow.


Federal Reserve – Fed says four, market says maximum two – I'm with Fed

Fed left it was late, probably too late, but the tone of the press conference and "dots" indicates Fed high believe in their forecasts.

Four hikes is on the cards for 2016, the market consensus is two hikes offered – the gap remains and for now the risky assets trades on fading the Fed.

Fed however do tend to deliver the promised hikes. An excellent piece "Historical lesson from Federal Reserve rate-hike cycles" from Allianz Global Advisors proves the point:


Most commentators of course thinks this time it's different – always is right?


Q4-GDP looks better and better, my favorite indicator: Fed Atlanta's GDPnow is now well inside the consensus:


The big question: Inflation or not?


The main "new information" I got from Chairwoman Yellen was her increased confidence in inflation picking up – here lies a potential "explanation" between Fed and market. Market simply does not buy higher inflation despite these headline recently:


Euro core inflation at two year high and overall core-inflation have not only increased by stayed closed to 2% at all times here is the link to Yellen direct answer to inflation

Meanwhile my main theme for Q3 and Q4 of this year – the price of capital rising continues – I don't need to remind you but it has been carnage.


Tactical

I leave 2015 risk wise very light on positions – my price signals is not flashing yet and the only optionality I will want to own is upside in crude (WTI), Gold/Silver and weaker US$.

It will take the market a week at least to "get…" the message that the cost of money has now started a move higher and probably much higher than most people can even imagine. 80% of all trader in the market today have never lived through a Fed hike cycle and the cost of capital needs to rise – the 57 trillion US$ of debt which has financed the meaker growth we have seen since 2009 now needs to be addressed.


Thank you,


Let me use this opportunity to say thank you to all the customers, investors, conference attendees, media and colleagues I have met in my busiest year ever.

I have been on the road for more than 120 days, been to more than 30 countries, but everywhere I am astonished how smart, open and engaged everyone is and this despite me often telling you that you are the dumbest generation ever, the most bland, the most average, and the least productive!

This ability to accept the discussion, for us to have the conversation has been the highlight for me and it's a sign of not only a willingness but also a commitment to move towards a mandate for change.

I wish all of you a happy holidays, may the presents be large and plenty,

Safe travels,


Steen "Santa Claus" Jakobsen


Med venlig hilsen  |  Best regards
Steen Jakobsen  |  Chief Investment Officer


Saxo Bank A/S  |  Philip Heymans Allé 15  |  DK-2900 Hellerup
Phone: +45 39 77 40 00  |  Direct: +45 39 77 62 23  |  Mobile: +45 51 54 50 00


Research: http://www.tradingfloor.com/traders/steen-jakobsen

Please visit our website at www.saxobank.com


This email may contain confidential and/or privileged information.
If you are not the intended recipient (or have received this email
by mistake), please notify the sender immediately and destroy this
email. Any unauthorised copying, disclosure or distribution of the
material in this email is strictly prohibited.

Email transmission security and error-free status cannot be guaranteed
as information could be intercepted, corrupted, destroyed, delayed,
incomplete, or contain viruses. The sender therefore does not accept
liability for any errors or omissions in the contents of this message
which may arise as a result of email transmission.

onsdag den 16. december 2015

2016 Outrageous Predictionsis out!

Dear All,


Please find the OP-2016 attached as PDF – and a presentation I use to explain them.


Hope you will enjoy it.


Safe travels,


Steen


Med venlig hilsen  |  Best regards
Steen Jakobsen  |  Chief Investment Officer


Saxo Bank A/S  |  Philip Heymans Allé 15  |  DK-2900 Hellerup
Phone: +45 39 77 40 00  |  Direct: +45 39 77 62 23  |  Mobile: +45 51 54 50 00


Research: http://www.tradingfloor.com/traders/steen-jakobsen

Please visit our website at www.saxobank.com


This email may contain confidential and/or privileged information.
If you are not the intended recipient (or have received this email
by mistake), please notify the sender immediately and destroy this
email. Any unauthorised copying, disclosure or distribution of the
material in this email is strictly prohibited.

Email transmission security and error-free status cannot be guaranteed
as information could be intercepted, corrupted, destroyed, delayed,
incomplete, or contain viruses. The sender therefore does not accept
liability for any errors or omissions in the contents of this message
which may arise as a result of email transmission.

torsdag den 3. december 2015

US Excess rate indicates MAJOR cycle turn ? Cost of capital RISING despite ECB and a slow FED


Interesting chart – the US "excess rate" in 10 yr. sector……hence the "cost of capital" for reserve/funding currency of choice…


A high – too high price of money- have a tendency to "kill growth" in rest of the world and hence spill over into lower markets, US$ and risk…..


Here its charted vs. the DXY index…  The excess rate follow Sinus-like progress from -50 to +50 – below/above creates reversals….


In other "divergence" is MAX-ed out presently…..


Another look here at 12 month (1 yr) – GDP weighted ….also… price of money rising..


Finally, credit space.. CCC – Junk has gone ballistic..


Even BAA – lowest investment grade keeps seeing rising yields…


Leveraged loans @ 2010/11 prices!!!!


Another divergence chart… EUR high yield vs. Global High Yield..


Med venlig hilsen  |  Best regards
Steen Jakobsen  |  Chief Investment Officer


Saxo Bank A/S  |  Philip Heymans Allé 15  |  DK-2900 Hellerup
Phone: +45 39 77 40 00  |  Direct: +45 39 77 62 23  |  Mobile: +45 51 54 50 00


Research: http://www.tradingfloor.com/traders/steen-jakobsen

Please visit our website at www.saxobank.com


This email may contain confidential and/or privileged information.
If you are not the intended recipient (or have received this email
by mistake), please notify the sender immediately and destroy this
email. Any unauthorised copying, disclosure or distribution of the
material in this email is strictly prohibited.

Email transmission security and error-free status cannot be guaranteed
as information could be intercepted, corrupted, destroyed, delayed,
incomplete, or contain viruses. The sender therefore does not accept
liability for any errors or omissions in the contents of this message
which may arise as a result of email transmission.